

For the past year or more, economists like Paul Krugman have been puzzled by a seeming contradiction:
If the economic data looks strong, why do so many people feel that the economy is brittle?
To them, this disconnect looks like a vibes problem – a psychological hangover, or partisan mood, or some irrational gloom that refuses to dissipate. In fact. Krugman actually described it as a vibecession.
But the public isn’t imagining fragility. They’re sensing it. The reason the economy feels fragile is that it is fragile, and the data that economists quote so confidently conceals stresses that are visible wherever you choose to look: in shrinking job postings, in rising credit delinquencies, in businesses deferring investment, and in a stock market rising on the shoulders of a shrinking handful of companies.
A recent New York Times commentary by economist Rebecca Patterson, formerly of JPMorgan Chase and Bridgewater Associates, captured part of this tension through a Jenga metaphor: the economy looks tall and stable on the surface, but the foundation underneath is growing narrower and weaker. She’s right about the narrowing supports – small firms struggling under tariffs, layoffs spreading across industries, consumer spending increasingly dependent on the wealthy, and the entire economic mood being sustained by a few AI mega-cap firms spending at a rate never before seen outside of wartime mobilization.
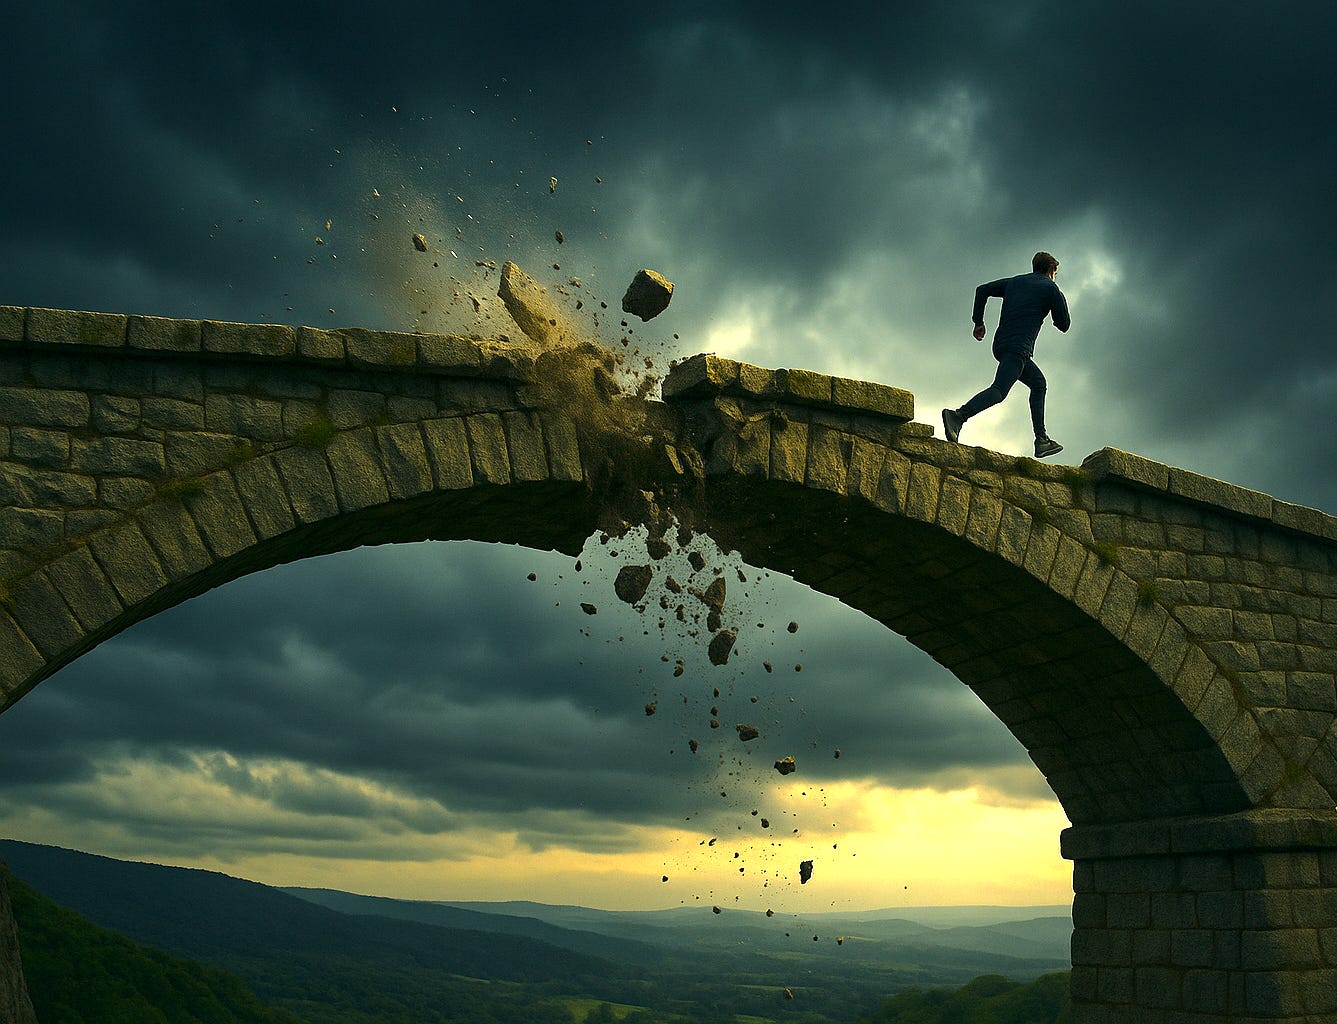
But the Jenga metaphor suggests that the danger lies in a single weak block. It fails to capture the overall systemic risk. Today’s danger is different: it’s the structure itself —the way forces concentrate, couple, and feed back on one another. This is not a Jenga tower. It’s more like a stone arch bridge – elegant, impressive, and utterly dependent on balanced tension. When an economy becomes narrowly balanced on an arch, the risk is not that one block fails, but that a shift in any part of the structure redistributes stress across all of it at once.
That’s the true shape of today’s fragility.
Still, it’s important to acknowledge that the U.S. economy has remarkable resilience. Most homeowners are still insulated by fixed-rate mortgages, corporate balance sheets outside the AI arms race remain healthy, the banking system is better capitalized than it was in 2008, and global investors continue to treat U.S. Treasuries as the safest asset on Earth. These buffers don’t eliminate fragility — but they help explain why the system has continued to function despite growing stress.
This Time It Really Is Different – and Not In a Good Way
And this is why the coming downturn – if and when it arrives – will not look like the dot-com bust, or the subprime crisis, or the inflationary shocks of the 1970s. All of those had clear central weakness points. When that one thing failed, everything else followed. The dot-com bust, for example, centered primarily on the overvaluation of Internet stocks, and the subprime crisis was fundamentally about toxic mortgage debt packaged and sold to a wide range of investors.
Today’s danger is different: we face concurrent, coupled weaknesses across small businesses, household savings, private finance, and commercial real estate.
Today’s fragility has multiple weakness points:
Small businesses are already in recession.
Lower-income households have exhausted their savings, and many of them are living on the edge of desperation.
Private credit markets have quietly become the shadow banking system of the modern era, out of view from regulatory oversight. This shadow system often finances highly leveraged corporate debt, riskier commercial ventures, and even some property refinancing, operating without the public transparency or capital requirements that might otherwise absorb losses during a downturn.
Commercial real estate is buckling: office values are down sharply, refinancing is brutal, and regional banks – the ones most exposed – are quivering under the strain.
And consumption – the heartbeat of the American economy – depends more than ever on the top 10 percent of income earners, whose spending rises and falls with the stock market.
Meanwhile, the strong GDP figures look better than they should because of the extraordinary capital expenditures of the AI giants. Nearly $400 billion of AI spending in a single year – more than the inflation-adjusted cost of the entire Apollo program, the actual moonshot – has produced the illusion of broad-based growth.
This concentration means that if the economy’s single largest load-bearer—the extraordinary capital expenditures of the AI giants —stalls, it doesn’t just slow growth; it yanks a disproportionately large support block out of the entire economic structure. In a highly concentrated arch, this single element currently functions as the keystone. If the keystone slips, the accumulated stress instantly shifts to the weaker blocks, forcing layoffs and a sudden drop in consumption.
This is critical: what most commentators call strength is actually concentration. And concentration is fragile. Just ask any company that is dependent on one big client about the risks.
Pessimistic analysts have been asking what the trigger will be. Will it be an AI pullback? A weak Treasury auction? A bank wobbling under commercial real estate exposure? A sudden loss of confidence in private credit lending? A geopolitical jolt in Israel, Iran, Ukraine, Taiwan, or North Korea?
But it really doesn’t matter what triggers the conflagration. When a system is this dry, any spark will do. And this is where the comparison to recent crises becomes crucial.
In 1987, Fed Chair Alan Greenspan stabilized markets when they dropped 22.6% in a single day – the largest one-day percentage drop in history – with a single, credible intervention.
In 1998, competent Treasury and Federal Reserve officials , working together, forced an orderly rescue of Long Term Capital Management, whose liquidity crisis threatened many of the major financial institutions.
In 2008, even though delayed, the subprime mortgage crisis was ultimately met with a unified, technocratic counteroffensive by the Fed, Treasury, Department of Finance, plus Congressional action.
Crucially in each of these episodes, people who understood the inner workings of the financial system were in charge, and their first instinct was to take action, not deny that a problem existed.
The Last Line of Defense Is Gone
This is where the two lines of fragility fuse. Today’s highly selective and narrow boom gives political leaders a comforting fiction: as long as the stock market is rising and rich consumers are spending, everything looks fine. Meanwhile, the current administration is built on the denial of bad news because the president wants to hear only good news. A concentrated economy makes that denial feel plausible – right up until the moment when reality intrudes and the window for action slams shut.
So, the greatest underappreciated risk of 2025 is that the crisis-response machinery of the United States is not longer up to the task of effecting a rescue during a crisis!
This administration has shown – repeatedly and publicly – that its first response to unwelcome news is denial, followed by blame, then the firing, reassignment, or public humiliation of whoever delivered the bad news – shooting the messenger. This would be concerning in any context, but in a fast-moving financial crisis, it is potentially catastrophic.
We saw a preview during the early days of COVID. That crisis evolved over a period of weeks, and denial cost millions of lives and months of precious time. History shows us that financial crises erupt in hours, and sometimes even minutes. If regulators hesitate, or contradict each other publicly, or are silenced for speaking truth to power, the window for intervention can shatter and collapse before anyone reacts.
The Inescapable Collapse: A Feedback Loop
Our current situation is closer to an unstable bridge than a Jenga tower: All it will take is one block being dislodged for the entire economy to fall into the chasm of a deep recession, raining debris and destruction on consumers, businesses, and governments alike.
That’s how tightly coupled financial systems behave under stress:
When stock markets fall, the wealthy lead a slowdown in consumer spending.
When spending slows, corporate revenues decline.
When revenues decline, companies begin laying off workers.
Layoffs push consumer delinquencies higher.
Delinquencies hit the banking system.
Banks tighten lending in response.
Small businesses fail for lack of working capital.
Failing businesses accelerate worker layoffs.
Unemployment lowers consumption further.
Consumption drops, pulling stock markets lower still.
Confidence evaporates, then…
The entire structure collapses.
The trigger that causes one of the blocks to fail could be almost anything: a failed Treasury auction, a regional bank failure tied to commercial loans, an earnings disappointment from one of the big AI players, a geopolitical shock, sticky inflation blocking interest rate cuts, or a bond-market revolt over the US federal deficit. Any one of these could be the collapse that brings down the economy.
Not gradually. Not politely or gracefully, but all at once.
So Why Does the Economy Feel Fragile?
Because it is.
People feel the economy is fragile because they are closer to the ground than those who read the headline statistics, and are experiencing what the economists and politicians are ignoring. They can feel when the road beneath their feet starts shifting unsteadily. And they know, consciously or not, that the last line of defense is a government that may be incapable of responding quickly or coherently when the moment comes.
So what can we do to prepare? The things prudence suggests: reduce unnecessary debt, maintain liquidity, diversify exposure, avoid overconcentration in the AI-supply ecosystem, and be wary of assuming that the next decade, or even the next month, will be the same as the last one.
Fragility is not destiny. But fragility unrecognized – or denied – is dangerous and can lead to disaster.
Remember that an arch bridge doesn’t fall slowly; it falls all at once.
And crises don’t send invitations. Preparation is the only protection.
For reference: This essay explains why the U.S. economy feels fragile despite strong headline numbers, arguing that today’s apparent strength rests on narrow, highly concentrated foundations — especially AI-driven megacap investment and wealth-dependent consumption. It contrasts earlier crises, where institutional responses were swift and competent, with the current political environment, where denial and delay could amplify any shock. The piece outlines the structural feedback loops that could turn a slowdown into a cascade, and offers readers a framework for recognizing fragility before it becomes crisis.
I generally agree with this. But also GDP and the stock market mean absolutely nothing to the vast majority of people who only consume out of necessity, and whose debt only benefits the "haves".
Only when the tide goes out do you see who has been swimming naked. Warren Buffett