

America’s stock market is very expensive by most measures.
The Buffett Indicator – the total value of listed U.S. stocks compared with the size of the underlying economy – is at levels that make historically literate investors nervous. But the danger is not spread evenly as stocks are not equally overpriced.
The S&P 500 and other major indexes are now disproportionately dependent on AI-linked companies: hyperscalers, chipmakers, cloud platforms, and the firms building the physical machinery of the AI boom. The broad market looks strong because the top of the market looks magnificent. That’s actually less an indication of general prosperity than of concentrated market risk.
The key question is not whether AI is useful; it already is. The question is whether the stock market has capitalized decades of enormous AI profits before those profits show signs of appearing.
Asking whether AI valuations are realistic is very different from asking whether AI is valuable.
But that’s a question the market does not want to ask.
This Is Not Pets.com
The widespread, but lazy analogy is the dot-com bubble. It is also largely wrong.
Microsoft, Alphabet, Amazon, Meta, Nvidia, Oracle, and the rest of the AI infrastructure ecosystem are not Pets.com. They are real companies, with real customers, real revenues, real engineers, and in many cases enormous cash flows.
That’s exactly why this matters.
Pets.com vanished without taking the bond market, the power grid, passive index funds, utility ratepayers, pension funds, data-center landlords, private credit, and municipal tax incentives down with it. The AI boom is different because it is being built by immensely valuable companies using real balance sheets, strong credit ratings, political influence, and index weight to take extreme risks in an infrastructure race whose economics are still unproven.
The danger is not fake companies selling illusory products. It’s that real companies, real technology, and real infrastructure are being financed against profits that may never arrive, and could take big pieces of the economy down with them.
Priced Like Monopoly Software, Built Like Railroads
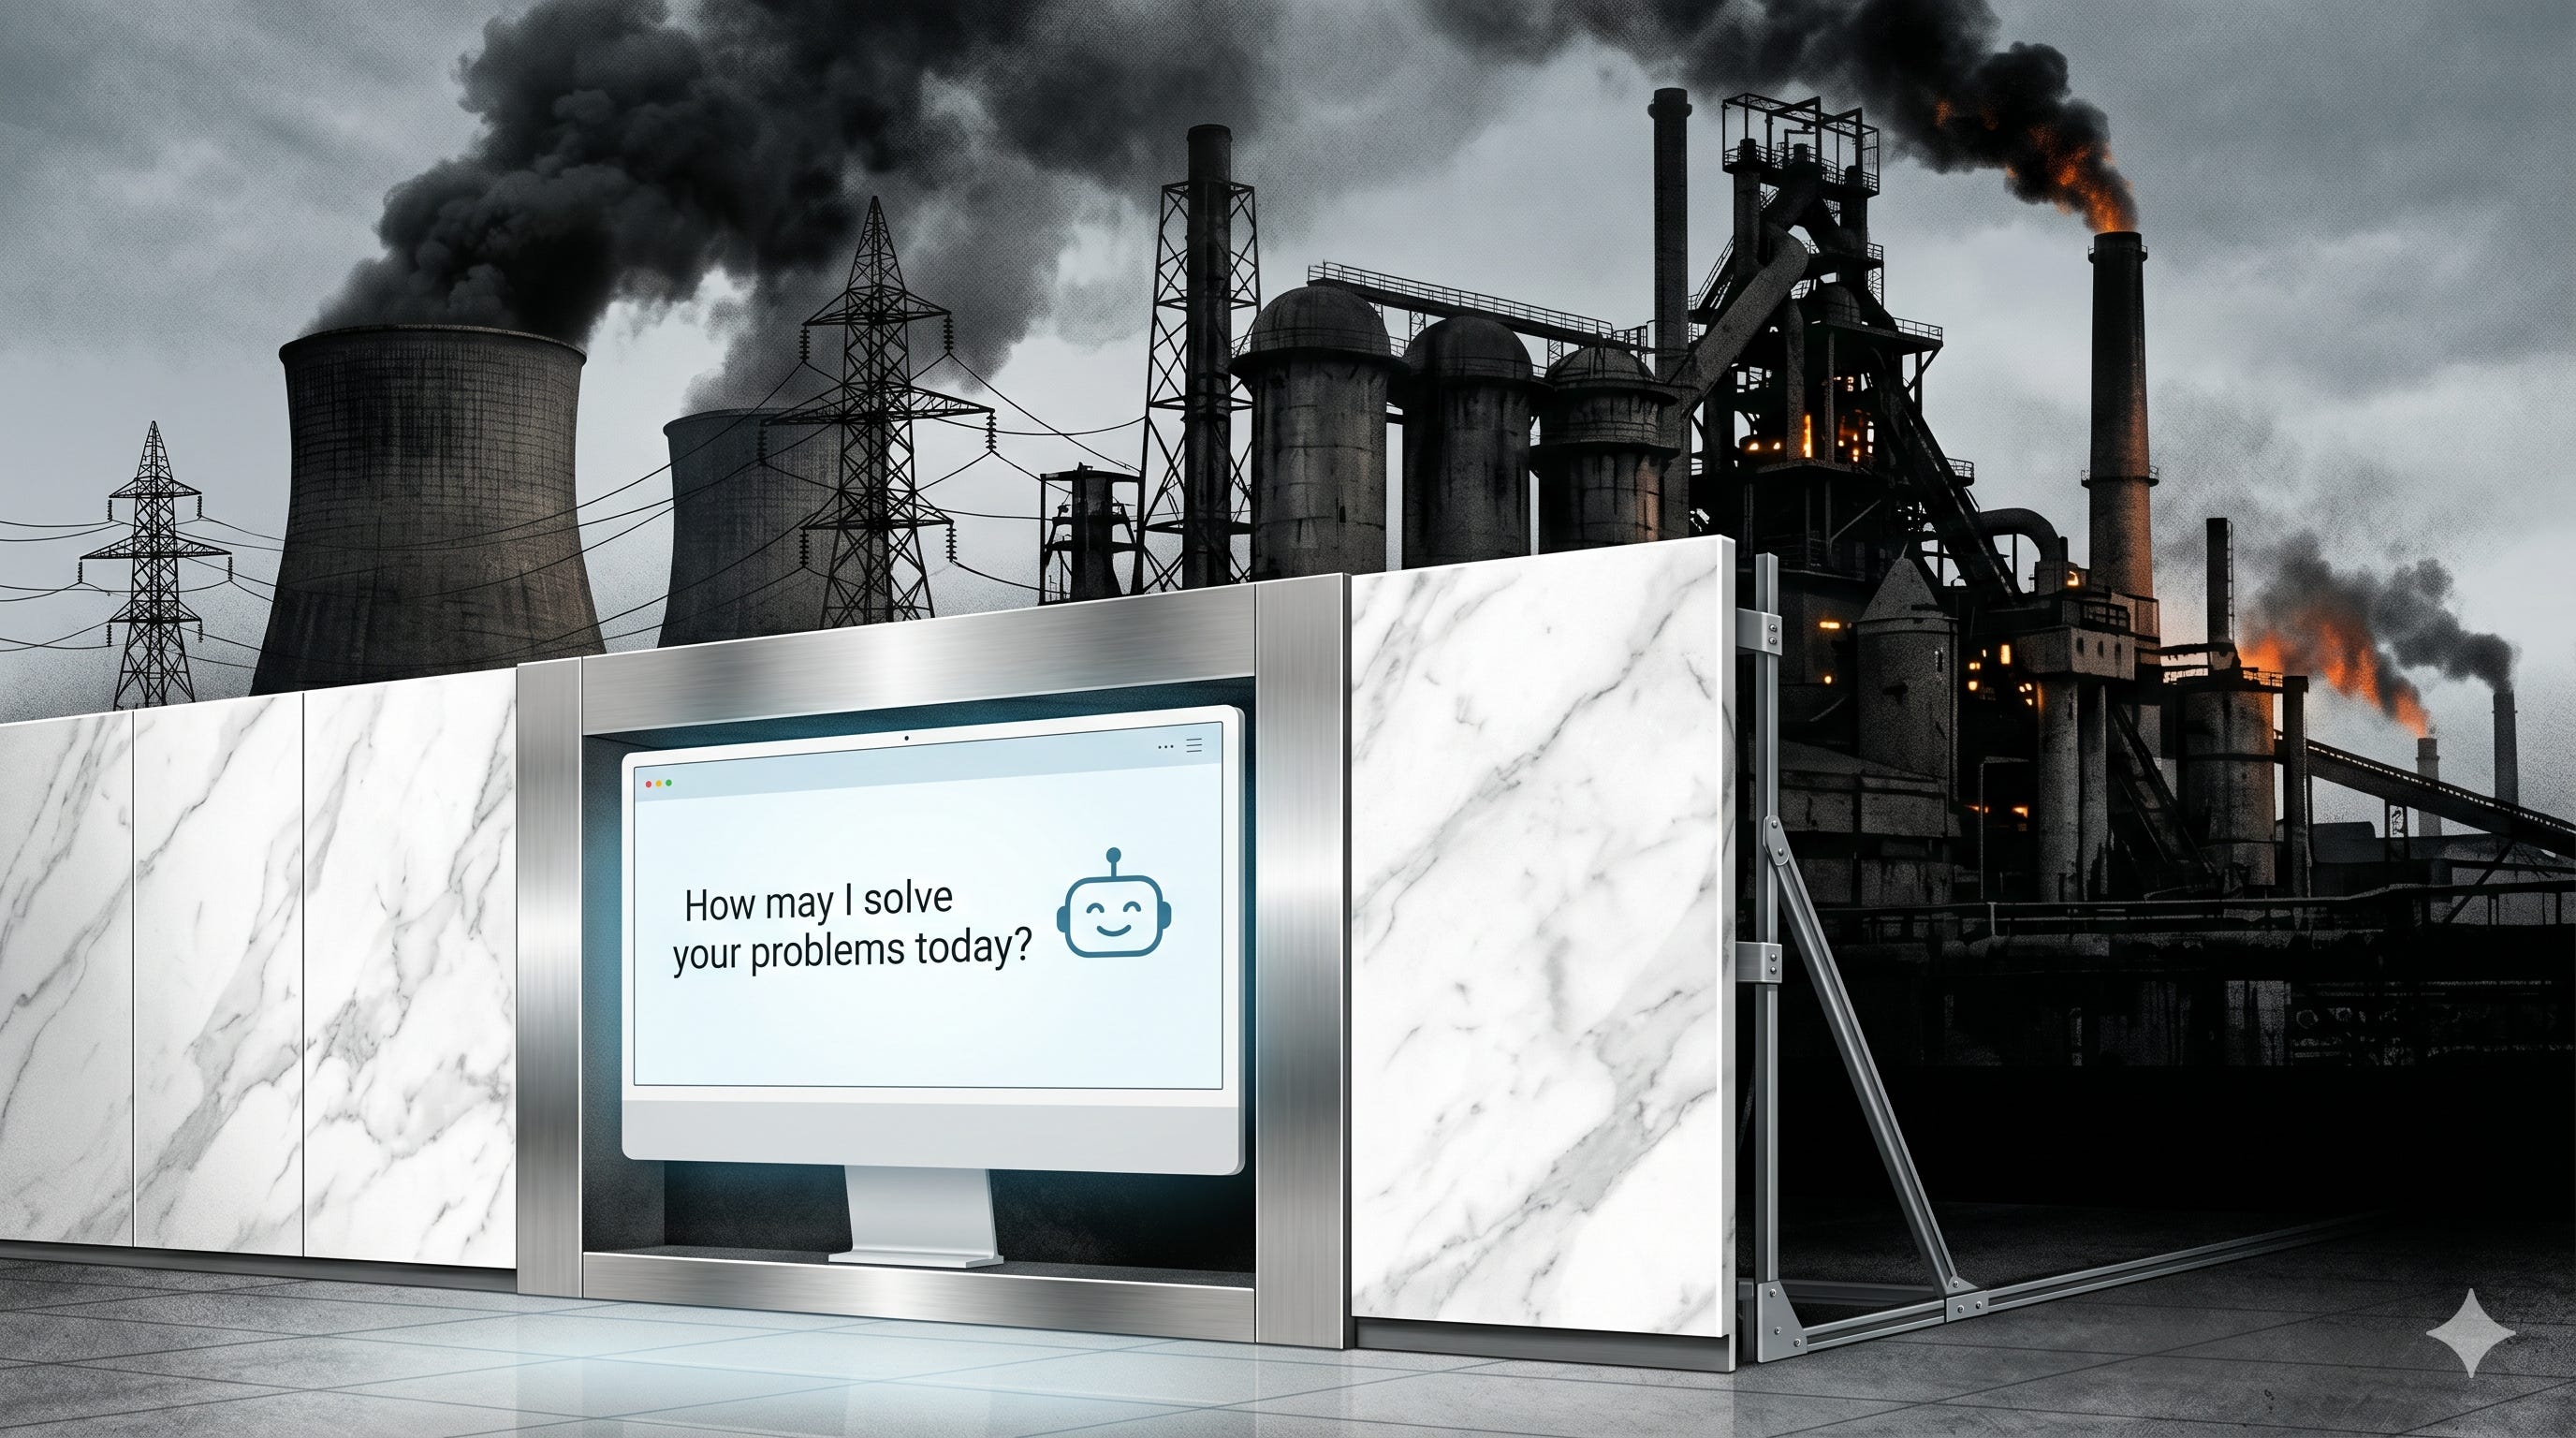
The market is pricing AI like monopoly software, while the companies are spending like railroads.
The dream being priced into these companies is not ordinary software. It’s monopoly software: infinitely scalable, asset-light, high-margin, winner-take-most software, with near-zero incremental cost per subscriber, and permanent pricing power.
But the AI buildout doesn’t look like that. It looks like high-overhead, capital-intensive heavy industry.
The AI boom requires data centers, chips, power, cooling, grid connections, financing, permits, and political cooperation. Such physical equipment depreciates, overheats, creates bottlenecks, and becomes obsolete. AI may be digital in use, but it’s industrial in appetite.
The market is still applauding as if this were an asset-light software story, but their spending is financing debt-huingry, heavy industry.
Revenue Is Real, but Profit Is the True Test
AI revenue exists. Consumers pay for subscriptions. Businesses pay for AI tools. Developers pay for APIs. Cloud customers pay for compute. None of that is imaginary.
But revenue is not profit, and limited early revenue is not a return on hundreds of billions of dollars of infrastructure spending. The serious question is whether durable, profitable, arm’s-length customer revenue can grow fast enough to produce a decent return on the capital being committed. The hyperscalers remain highly profitable in their legacy businesses, but they haven’t shown profitability in their AI investments. They are projecting it, and at extraordinary rates.
That matters because a company can be profitable while a massive new investment cycle eats its future free cash flow. For years, the largest technology companies were cash machines. They funded growth, bought back stock, and maintained pristine balance sheets.
AI changes that machine. The warning sign is not that these companies stop making money. The warning sign is that they keep making enormous amounts of money yet still need outside capital because the AI buildout consumes cash as fast as the old businesses produce it.
A company that once funded itself internally begins to look less like asset-light software and more like a railroad, utility, semiconductor fab, or telecom network. It may still be valuable, but it no longer warrants the the same valuation multiples.
There’s also a market consequence. For years, Big Tech buybacks helped support the market value of their stocks. But every dollar spent on AI data centers is a dollar not spent buying back stock. That’s a different bargain, and the market has not recognized the difference.
The Circular-Demand Facade
Some of the demand validating the AI boom appears to be circular, or financially engineered, looking less like ordinary customer demand and more like carefully painted financial false-fronts.
The loop can look like this: a hyperscaler invests billions in an AI startup. That investment helps validate a higher startup valuation, making the hyperscaler’s earlier stake look more valuable. The startup then uses part of the money to buy future cloud compute from the hyperscaler. The hyperscaler reports cloud revenue growth. The result is that investors see escalating cloud revenues, soaring AI valuations, expanding capital spending, steadily rising stock prices, and conclude that the AI future has been validated.
But how much outside cash has actually entered the system?
This isn’t necessarily fraud, but it requires incentives, and there are billions of dollars in incentives to go around. Startups, hyperscalers, chipmakers, bankers, utilities, data-center developers, politicians, and investors all have reasons to keep the wheel spinning because they are all better off when it does.
The machine does not need a mastermind. It only needs every participant to do the narrowly rational thing: build, borrow, mark up, extrapolate, and pass the risk forward.
That is how bubbles often work – not by inventing something useless, but by taking something useful and financing it as though future profits were guaranteed and enormous.
What If the Architecture Is Wrong?
The most dangerous possibility is not that AI fails. It is that AI succeeds in a cheaper form than the hyperscalers are building.
The current hyperscaler strategy assumes that the winning path requires ever-larger models, clusters, data centers, ever-more-expensive chips, and ever-greater energy consumption. They may be right, but what if they’re not?
What if the profitable AI future is smaller, cheaper, more specialized, more local, more efficient, and merely “good enough” for most tasks? For instance, what if China’s AI-light approach, or some future version of it, shows that most economically useful AI does not require the most extravagant infrastructure? What if smaller models, better training methods, edge inference, open-source systems, synthetic data, algorithmic efficiency, or specialized tools deliver most of the value at a fraction of the cost?
Then the hyperscalers may not just be overbuilding. They may be building the wrong kind of machine.
The railroad bubble at least left railroads. The optical fiber bubble at least left fiber. An AI infrastructure bubble may leave some useful data centers, but it may also leave warehouses full of rapidly depreciating GPUs, stranded power commitments, obsolete cooling designs, and facilities optimized for a compute architecture the market has already moved beyond.
GPUs do not age like rail lines. They age like milk in the carton.
A chip bought today may be second-rate in three years and financially useless before the obligations attached to it have been paid off. At that point, they’re not software assets. They’re stranded assets, and deadweight on a balance sheet.
The Winner-Takes-Most Trap
Strategically, the hyperscalers seem to be behaving as if they have no choice. If AI becomes the next dominant computing platform, no major tech company wants to be left behind. Each company may be making a rational decision from its own perspective, but together, they may be building a disaster.
This is the prisoner’s dilemma of the AI boom. If one company builds and the others hesitate, the builder might win. If all of them build, they may collectively create too much capacity, too much debt, too many power commitments, and too many assets chasing too little profitable demand.
And if AI turns out to be a winner-takes-most market, the problem becomes worse. One or two companies may win. The rest may discover that their investments were too late, second-rate, or wasted.
That is how a seemingly rational arms race becomes a financially irrational industry.
Yet the market is not pricing that possibility. It’s pricing broad triumph, even though history suggests broad triumphs are rare as hen’s teeth.
The Tripwires
No one can time a market crash with confidence, but you can watch for stress in the systems.
The first tripwire is capital spending consuming operating cash flow. If AI infrastructure spending absorbs most of the cash these companies generate, buybacks shrink, debt rises, and software-monopoly multiples become harder to defend.
The second is credit-market tiering. The strongest companies may still borrow cheaply for a while, but weaker AI infrastructure names will show stress first, such as Oracle, neoclouds, data-center developers, landlords, private-credit vehicles, and companies relying on debt-like obligations.
The third is repricing in data-center and utility finance. Leases, asset-backed securities, power-purchase agreements, utility rate-base commitments, and grid upgrades may begin to be rated less like safe infrastructure investments and more like high-tech risk in disguise.
A single disappointment could be enough: a hyperscaler cutting spending guidance, an AI lab missing revenue targets, a debt-heavy infrastructure player struggling to refinance, a utility regulator rejecting cost recovery, or a major company admitting that AI revenue is growing while margins and free cash flow deteriorate.
That’s when the story changes, and when it changes, market multiples change with it.
How the Danger Spreads
The danger does not stay neatly inside the AI names, because the hyperscalers and AI leaders dominate the major indexes. A sharp fall in their shares would automatically drag those indexes lower.
That’s the first effect: pure arithmetic. The second is market plumbing.
If falling mega-cap stocks trigger ETF redemptions, margin calls, volatility targeting, risk-parity deleveraging, hedge-fund de-risking, or institutional rebalancing, selling can spread far beyond the original offenders. In a crisis, funds sell what they can sell, not only what they want to sell. Liquid winners get sold to cover illiquid losers. Boring companies get dragged into frightening disasters.
There’s an old Wall Street aphorism: when the paddy wagon rolls up, it takes all the players.
That’s how a bubble concentrated in a few overextended companies becomes a broad-market event:
First the leaders collapse.
Then the index cracks.
Then liquidity dries up.
Then everyone discovers how diversified they weren’t. The hyperscalers were hidden in the indexes and propped up the index values – until they didn’t.
The Official Incompetence Risk
There is one more risk, and it’s an uncomfortable one.
Financial crises require fast, credible, technically competent responses from regulators. When credit markets break, reassurance only works if markets believe the people at the controls understand the machinery: Treasury markets, repo, bank capital, clearing, liquidity facilities, collateral, margin, insurance, derivatives, and regulatory coordination.
If investors conclude that the officials at the wheel were chosen for loyalty rather than competence, happy-talk not only doesn’t calm the market. It tells sophisticated investors that no one up top knows what they’re doing.
That’s not a partisan point. It’s a market-confidence point.
Markets can tolerate bad news. They cannot tolerate the suspicion that there is no one competent in the control room.
The Bill Comes Due
The danger is not that AI is fake. The danger is that Wall Street has treated AI’s future profits as if they were already in the bank, then used that assumption to finance the next round of pipe dreams.
But future profits are not today’s cash flow. Market capitalization is not collateral. Revenue is not return on investment. Strategic necessity is not the same thing as profitability.
Those distinctions disappear near market tops, then return in a rush as the markets correct and crash.
AI may change the world. Some companies will make fortunes from it. Some of today’s infrastructure will prove useful, even essential.
But if the market has priced the whole future into a handful of stocks, while those same companies are borrowing, building, and depreciating their way into a much harder and less forgiving business model, then the reckoning will not be bottled up inside the AI trade.
The dream may be digital, but the bill will have to be paid in cold, hard cash.
Summary: This post argues that AI is real and useful, but the stock market may be mispricing the AI boom by valuing hyperscalers as if they were capital-light monopoly software companies while they are increasingly building debt-hungry, capital-intensive industrial infrastructure. The risk is not that AI has no value, but that future profits may already be priced into a handful of dominant stocks before the cash flows exist. The piece examines concentration risk in major indexes, circular AI demand, unproven AI profitability, cash-flow strain, reduced buyback support, architecture risk from cheaper “good enough” AI, winner-takes-most overbuilding, credit-market tripwires, and the possibility that an AI repricing spreads through indexes, liquidity, and market confidence.
Thanks once again for helping us think through the complexity of this. 🇨🇦
I love this paragraph
The dream being priced into these companies is not ordinary software. It’s monopoly software: infinitely scalable, asset-light, high-margin, winner-take-most software, with near-zero incremental cost per subscriber, and permanent pricing power.
But the AI buildout doesn’t look like that. It looks like high-overhead, capital-intensive heavy industry.